

TL; DR
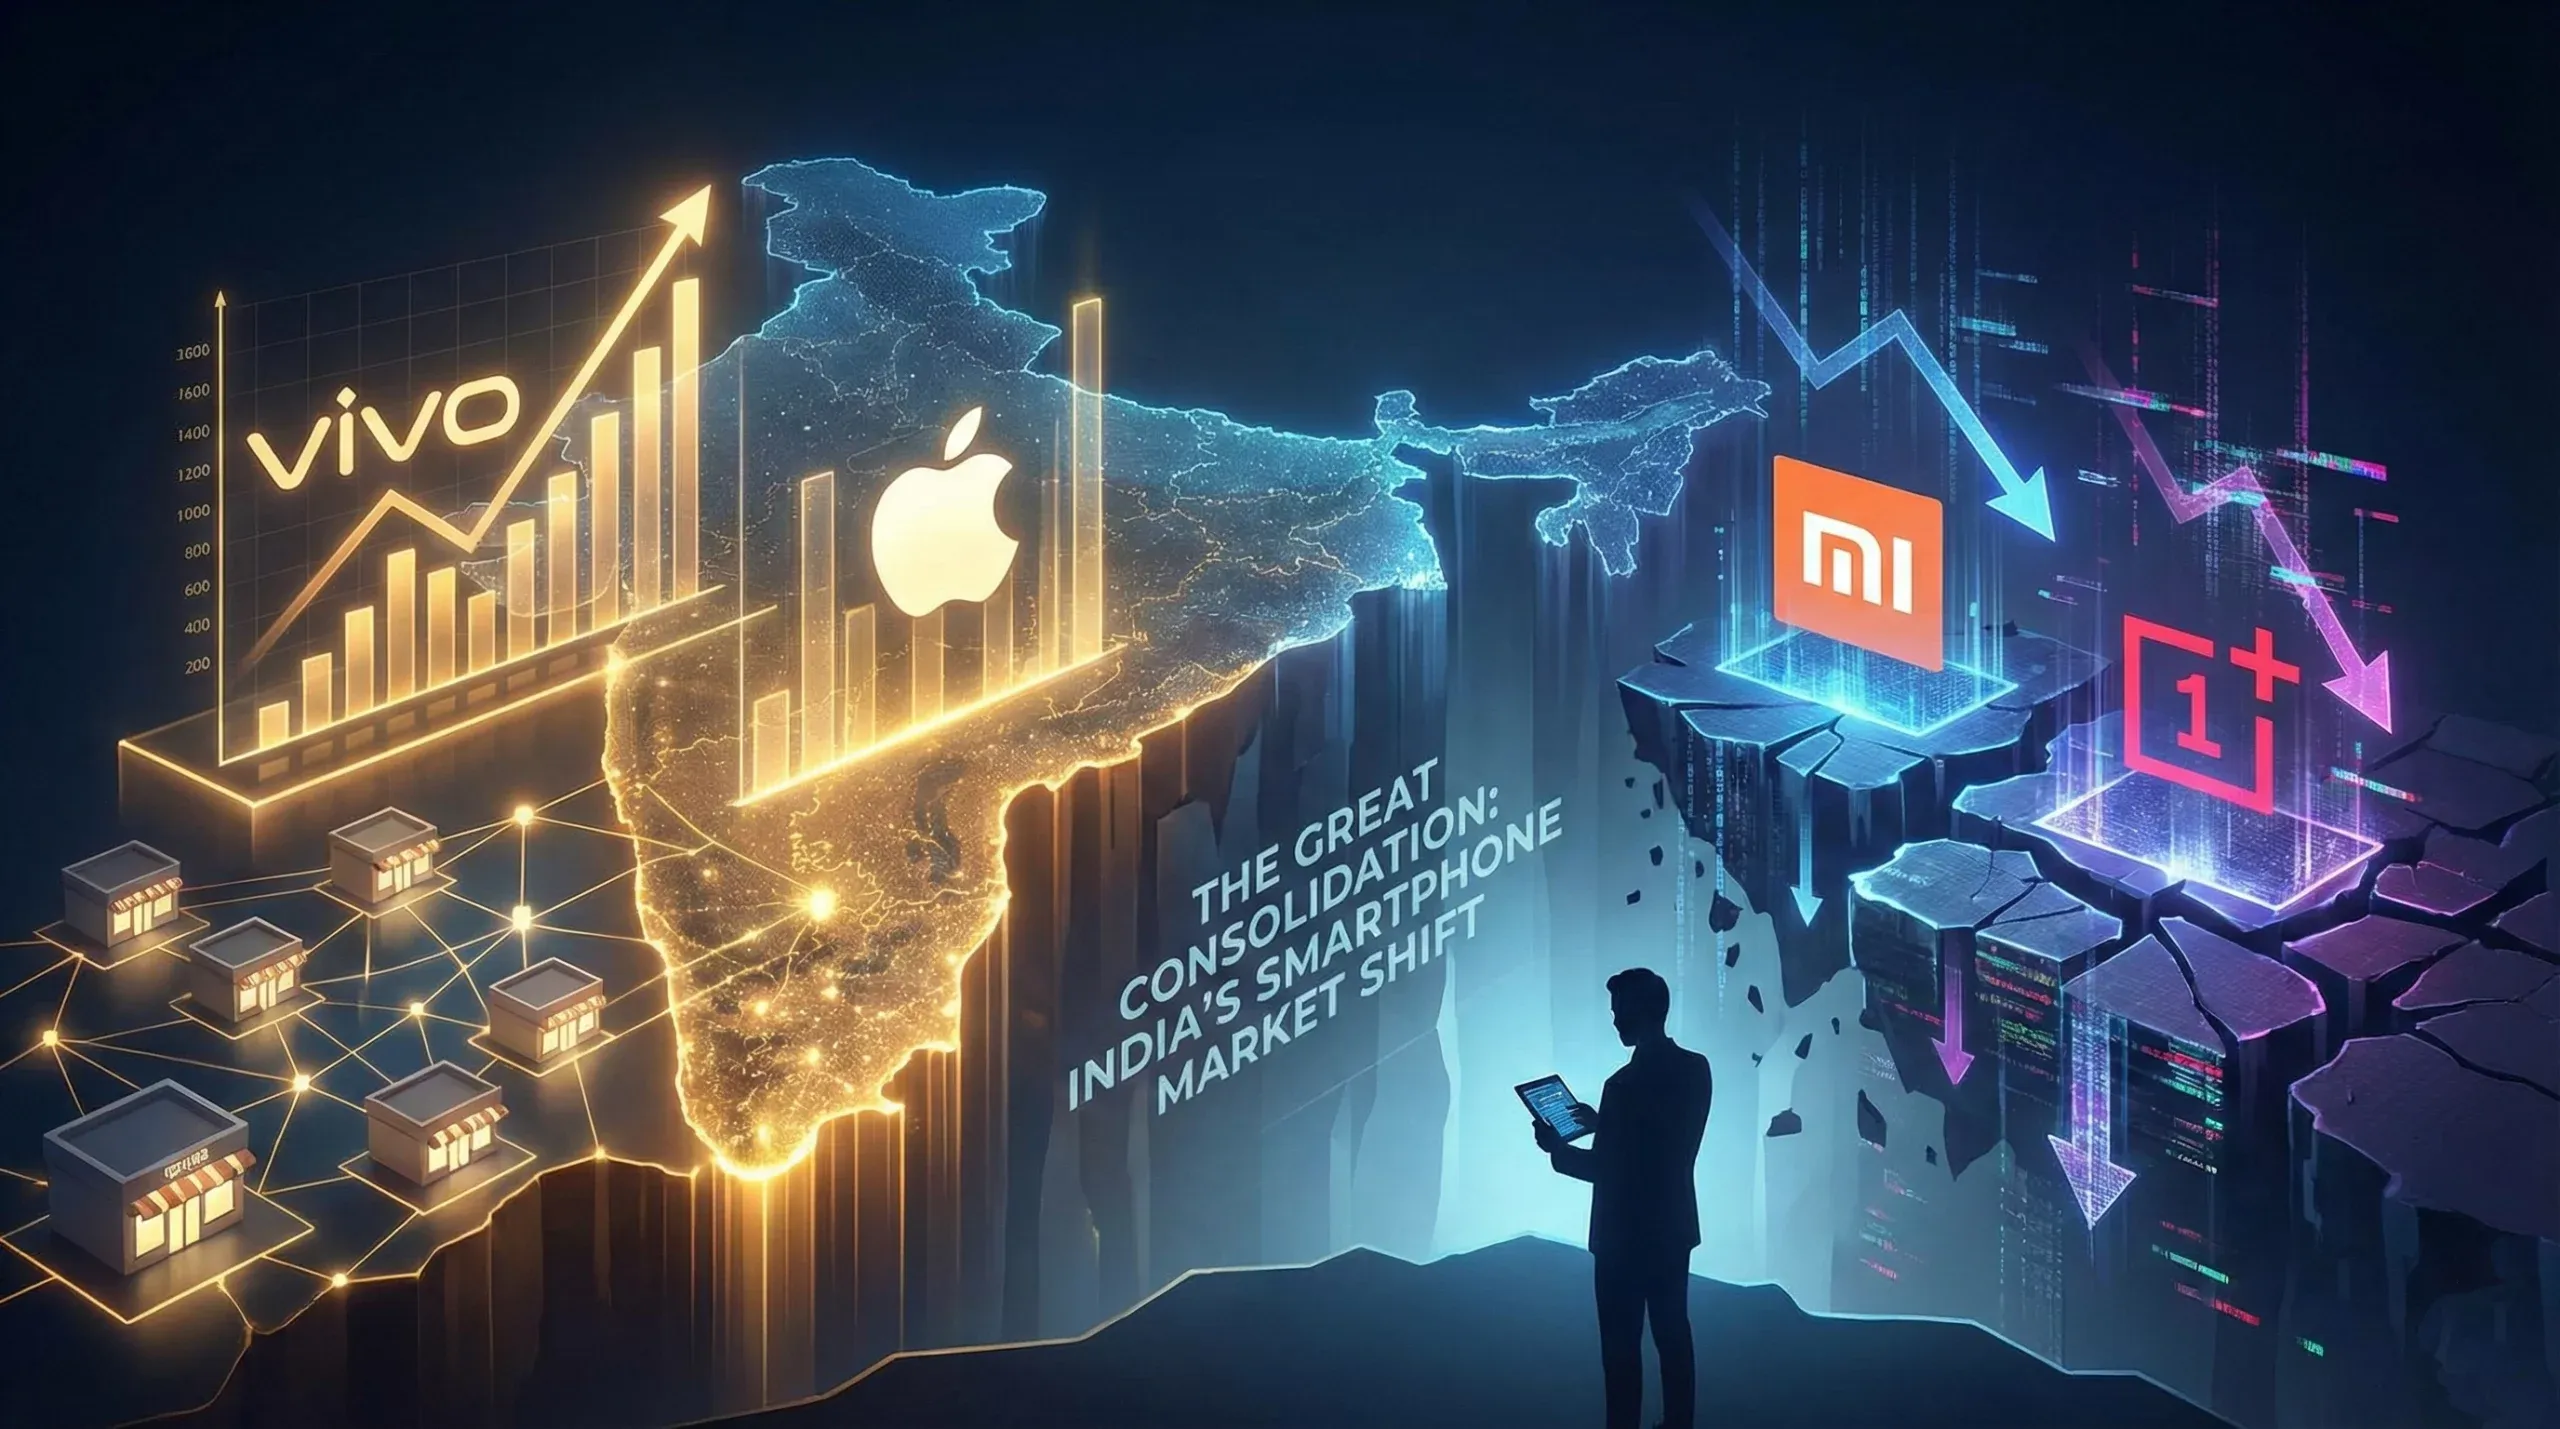
- vivo has seized 19.3% of the market by winning the offline margin war.
- Apple’s 15.5% growth is being driven by an infrastructure shift in EMI financing rather than by product demand alone.
- OnePlus and Xiaomi are facing a structural “identity crisis” that could lead to a permanent decline in market share.
India’s smartphone market just finished a year of brutal consolidation. While the total market barely budged, growing a microscopic 0.5%, the landscape underneath has been completely transformed. The era of cheap, online-first dominance is being stifled by a new reality: if you don’t have a massive retail footprint and a premium story to tell, you’re losing. And the softness became even more visible toward the end of the year, with shipments falling a noticeable 5% year-on-year in Q4 2025 — a clear signal that momentum weakened even as structural shifts accelerated.

What vivo’s 19.3% Actually Means
IDC reports vivo at 19.3% market share, up from 16.6% the prior year. That 2.7-point gain sounds modest in isolation. It isn’t. In a market that grew by just 0.5% in total, every share point vivo gained came directly out of a competitor’s pocket. This is zero-sum growth, and vivo won it.
IDC’s data doesn’t explain itself, but the pattern is legible. vivo’s gains are overwhelmingly concentrated in mid-range price bands and offline retail — the exact channels where other Chinese OEMs were either pulling back investment or distracted by regulatory and financial headwinds. Our read is that vivo filled that vacuum deliberately, not by accident.
The company operates a hyper-localized, agent-led distribution model with on-the-ground promoters embedded in tier-2 and tier-3 towns across India. More importantly, they backed this with retailer margin protection and inventory clearance guarantees, which means every shopkeeper had a financial incentive to push vivo over the competition. When the total market stops growing, that kind of last-mile loyalty becomes structurally decisive.
“The brands at the top aren’t playing in a single price corridor. They’ve architected portfolios that stretch from ultra-affordable devices, where profitability is razor-thin, and scale is everything, all the way up to halo-tier Ultra and Pro models commanding premium ASPs (and everything in between). That dual-front presence matters. It allows them to extract volume at the base of the pyramid while capturing disproportionate value at the top.” Independent Market Analyst, Yogesh Brar said.
Apple at 9.5%: The Number Nobody Adequately Explains
IDC reports Apple at 9.5% unit share, up from 8.2% — a +15.5% unit growth rate. Every analyst will predictably credit the iPhone 16 lineup. We think that explanation is incomplete and somewhat lazy.
The structural driver is financing. Roughly 40% of smartphone purchases in mainline Indian retail are now completed via EMI schemes. Apple’s domestic manufacturing footprint — partners Tata and Foxconn are now exporting over $50 billion in iPhones annually — gives the company pricing flexibility it simply didn’t have two years ago. A phone that once sat behind an ₹80,000 psychological barrier is now a manageable monthly payment for a much wider slice of Indian consumers.
Meanwhile, IDC data shows the ₹30,000+ segment grew 11% even as the overall market flatlined. Apple is the primary beneficiary of premiumisation — but it’s benefiting from an infrastructure shift, not just aspirational demand.
“Apple didn’t win India in 2025 on product alone. It won because the financial infrastructure of Indian retail finally caught up to its price points.” Brar said.

Motorola’s +33.5% Is the Anomaly Worth Investigating
Of all the figures in IDC’s tracker, Motorola’s growth is the one most likely to be dismissed as noise. It shouldn’t be.
Xiaomi, Poco, and realme all lost share at the same time — creating a gap in the ₹15,000–₹25,000 band where buyers were looking for dependable options without constant software shifts, overlapping sub-brands, or the uncertainty of flash-sale-driven availability.
Motorola’s bang-for-the-buck hardware became a genuine differentiator in this context. Indians are holding phones for 24–30 months, which means hardware stability matters more than launch-week benchmark scores. Brands that delivered consistency — Motorola being the clearest example — are now seeing it reflected in their shipment numbers.
“I’d caution against reading Motorola’s surge as a full brand renaissance. A meaningful portion of this growth appears to be opportunistic share capture from competitor stumbles rather than earned consumer loyalty. If Xiaomi resolves its regulatory situation and refocuses its mid-range lineup, some of those Motorola gains are structurally at risk,” says Brar.

The Xiaomi and OnePlus Collapses Are Not the Same Story
Xiaomi (-24.8%): External Wounds, Internal Paralysis
IDC shows Xiaomi falling from 12.0% in 2024 to 9.0% in 2025. In terms of rank, Xiaomi was tied for third place entering 2025 and ends the year at sixth. That is a complete structural demotion, not a soft quarter.
Our read is that the proximate cause is regulatory. Xiaomi has been navigating approximately ₹4,700 crore in frozen funds amid government investigations. That kind of legal cloud doesn’t just hurt brand perception — it weakens distributor confidence, slows product rollouts, and makes channel partners cautious at a time when offline reach is shaping results. Xiaomi has been fighting on the wrong front.
There’s a compounding product problem, too. The brand that once engineered devices specifically for Indian consumers has been shipping increasingly generic global SKUs during this period. In a market that rewards localization and responds to channel investment, that’s a self-reinforcing error.
OnePlus (-38.8%): A Self-Inflicted Identity Crisis
OnePlus is a fundamentally different failure. IDC shows it dropping from 3.9% to 2.4% share, and it is now smaller than iQOO, a brand that didn’t independently exist five years ago and was incubated within the same BBK group.
This is what happens when a brand systematically abandons the narrative that built it. OnePlus was constructed on a specific promise: flagship-grade hardware at non-flagship prices, delivered through a software experience (OxygenOS) that enthusiasts considered superior. That identity has been dismantled through repeated integrations with ColorOS. Today’s OnePlus software is functionally indistinct from OPPO’s — and that’s precisely the problem.
Performance-focused buyers shifted to iQOO, which now owns the hardware-first narrative that once defined OnePlus. Premium upgraders gravitated toward Samsung and Apple, brands with the credibility that OnePlus was attempting to build. The outcome: a brand without a clearly defined audience and sharply declining volumes.
“The BBK ecosystem — which owns vivo, OPPO, realme, iQOO, and OnePlus — appears to have made a deliberate internal resource allocation decision. vivo and iQOO are growing. OnePlus is not. It is very difficult to look at this data and conclude that OnePlus’s decline is accidental rather than a managed strategic outcome within the group. That should be the first question anyone asks OnePlus leadership in 2026.” says Brar.
The Offline Channel Is Back. It Never Really Left.

IDC reports that India’s offline channel hit its highest shipment levels in six years in 2025, growing 12% YoY and expanding market share to 57% — up from 51% in 2024. In the same period, the online channel’s share fell from 49% to 43%, with shipments dropping 12% YoY. That’s not a rounding error. That’s a structural reversal.
The narrative that India’s smartphone market was inexorably moving online was largely constructed during the COVID period, when physical retail was disrupted, and flash-sale mechanics dominated headlines. IDC’s 2025 data suggests that it was a temporary anomaly dressed up as a permanent trend.
The real structural driver of offline’s resurgence is margins. According to IDC, attractive trade margins and consistent cross-channel pricing fuelled the offline expansion throughout 2025. Retailers who felt squeezed by aggressive online pricing during 2022–2024 have been actively backed by brands, particularly vivo and OPPO, willing to protect their margin stack. When the economics of selling offline improve, distribution follows.
There’s a segment dimension to this too. IDC report sugggest that e-tailers remained competitive in the premium segment, where festive promotions were concentrated. But entry-level and lower mid-range Android devices faced weaker upgrade demand online — the segment where online had previously dominated through flash sales. That volume didn’t evaporate; it moved to the counter.
While commenting on IDC report, Brar said, “This is the single most important structural finding in IDC’s 2025 data, and it’s the one that most directly explains why vivo won and why Xiaomi lost. Offline is now the decisive battleground for volume in India. Brands that invested in channel economics, margin protection, distributor incentives, and physical presence are growing. Brands that were distracted, underinvested, or over-reliant on online sales are not. This isn’t a new lesson; it’s an old one that the industry forgot for three years.”
The Chipset War: Qualcomm’s Quiet Surge

Another interesting finding that emerged from the IDC report is the sharp surge of Qualcomm in the smartphone market. Snapdragon-based smartphone shipments grew 23% YoY in 2025, pushing their market share to 30%. MediaTek, the long-dominant chipset supplier in India’s budget and mid-range segment, saw its share drop from 54% to 46% — a 15% decline in absolute shipments. That swing of nearly 8 percentage points in a single year is not a blip.
Qualcomm’s growth has to do with strong shipments from Xiaomi, POCO, OPPO, and Nothing. It seems weird, right? Xiaomi and POCO are losing out, but they’re still helping Qualcomm. It makes sense when you look at what people are actually buying. More people bought the higher-end Qualcomm phones, while the cheaper MediaTek ones weren’t selling as well because people aren’t upgrading as much.
So, what’s really happening here is kinda interesting. MediaTek’s drop isn’t about their chips being bad; it’s about people just not buying as many cheap phones. Those folks who used to get ₹8,000–₹12,000 MediaTek phones are either keeping their old ones or skipping upgrades. The market’s shrinking at the bottom, and everyone’s moving up. Qualcomm is basically winning by default because of that shift.
“For MediaTek, this is a warning signal that deserves serious attention. Their dominance was built on volume at the low end — a segment that is structurally contracting. Their response will likely be to push aggressively into the ₹15,000–₹25,000 range with higher-performance Dimensity chips, which is already underway. But Qualcomm’s 23% growth suggests that the window is narrowing faster than MediaTek may have anticipated.”Brar said.
2026 Outlook: Brand by Brand
vivo
The offline moat is real, but it’s not permanent. Samsung and OPPO are watching vivo’s distribution playbook closely and have the capital to replicate it. The question for 2026: can vivo build credible premium brand equity above ₹30,000 before rivals close the gap at ground level? Without that, vivo risks owning the high-volume, low-margin end of a market that is structurally shifting upmarket.
Xiaomi
The regulatory cloud has to lift before any product strategy can land. Xiaomi’s core competency — aggressive value engineering — remains intact, but it cannot be activated while distributor confidence is damaged. A clean legal resolution in H1 2026 is the single most important variable for Xiaomi’s market position. Without it, another year of distracted product execution means Motorola and OPPO consolidate those gains permanently.
OnePlus
The identity decision cannot be deferred another year. At 2.4% share, OnePlus is approaching the threshold where distribution partners begin questioning shelf-space allocation. Either recommit to the performance-enthusiast audience with a genuinely differentiated software and hardware experience — or explicitly reposition into the ₹20,000–₹35,000 mainstream with a coherent brand story. The current middle-ground strategy is a managed decline. If BBK is intentionally running OnePlus down, it should say so. If it isn’t, the next 12 months are the last window.
Apple
The 9.5% figure will look conservative by end-2026 if EMI penetration extends into tier-3 cities. Apple’s India constraint was never product desire — it was price accessibility. The financing infrastructure is solving that problem. The iPhone 17 launch will matter less than the banking partnerships Apple quietly secures over the next six months. Watch the EMI desk, not the keynote.
Motorola
Don’t confuse this momentum with brand equity. Motorola’s 33.5% surge was substantially enabled by competitor stumbles, not earned loyalty. The risk in 2026 is overconfidence. Sustained growth requires investment in brand-building that makes consumers actively choose Motorola — not just accept it when the alternatives look unstable. That’s a harder problem than capturing opportunistic share.
OPPO
OPPO is arguably the most underread story in this entire dataset. IDC shows it at +11.1% growth and 13.3% share — a brand quietly climbing without the narrative chaos of its BBK siblings. OPPO has been methodical: consistent offline investment, a coherent mid-to-premium product ladder, and zero regulatory distraction. The 2026 question isn’t survival — it’s whether OPPO can articulate a brand identity that’s genuinely distinct from vivo at the consumer level. Right now, both brands serve similar demographics through similar channels. As the market premiumises, that overlap becomes a strategic liability for both.
iQOO
QOO’s modest +7.0% growth to 3.6% share understates its strategic importance within the BBK group. It is now larger than OnePlus — the brand it effectively displaced as the performance-enthusiast choice — and it got there by staying relentlessly focused on a single value proposition: raw hardware performance at aggressive price points. The 2026 risk for iQOO is mission creep. As it grows, the temptation to chase broader audiences with lifestyle features and watered-down positioning will intensify. The brands that beat iQOO in the long run won’t outperform it on specs — they’ll out-narrative it. Staying sharp on identity is the discipline iQOO cannot afford to lose.
Nothing
The 45% growth rate is genuinely exciting — but Nothing’s real test hasn’t started yet. It has built a devoted enthusiast base and a distinctive brand identity, both of which are enormously valuable. The question for 2026 is whether Nothing can scale into offline retail without diluting what makes it Nothing. The brand’s transparent design and opinionated software have zero tolerance for compromise. The moment it starts making distribution-first product decisions — cheaper materials, blander software, lower price points to chase volume — the magic evaporates. Watch whether their retail expansion strategy preserves the brand covenant or trades it away for market share numbers.
You can follow Smartprix on Twitter, Facebook, Instagram, and Google News. Visit smartprix.com for the latest tech and auto news, reviews, and guides.